Qualifying for a mortgage isn't always as simple as providing pay stubs, W-2s, or tax returns.
For some borrowers, significant financial resources are held in savings accounts, investment portfolios, or retirement funds rather than reflected in recurring employment income.
Fortunately, alternative mortgage programs may provide additional financing opportunities.
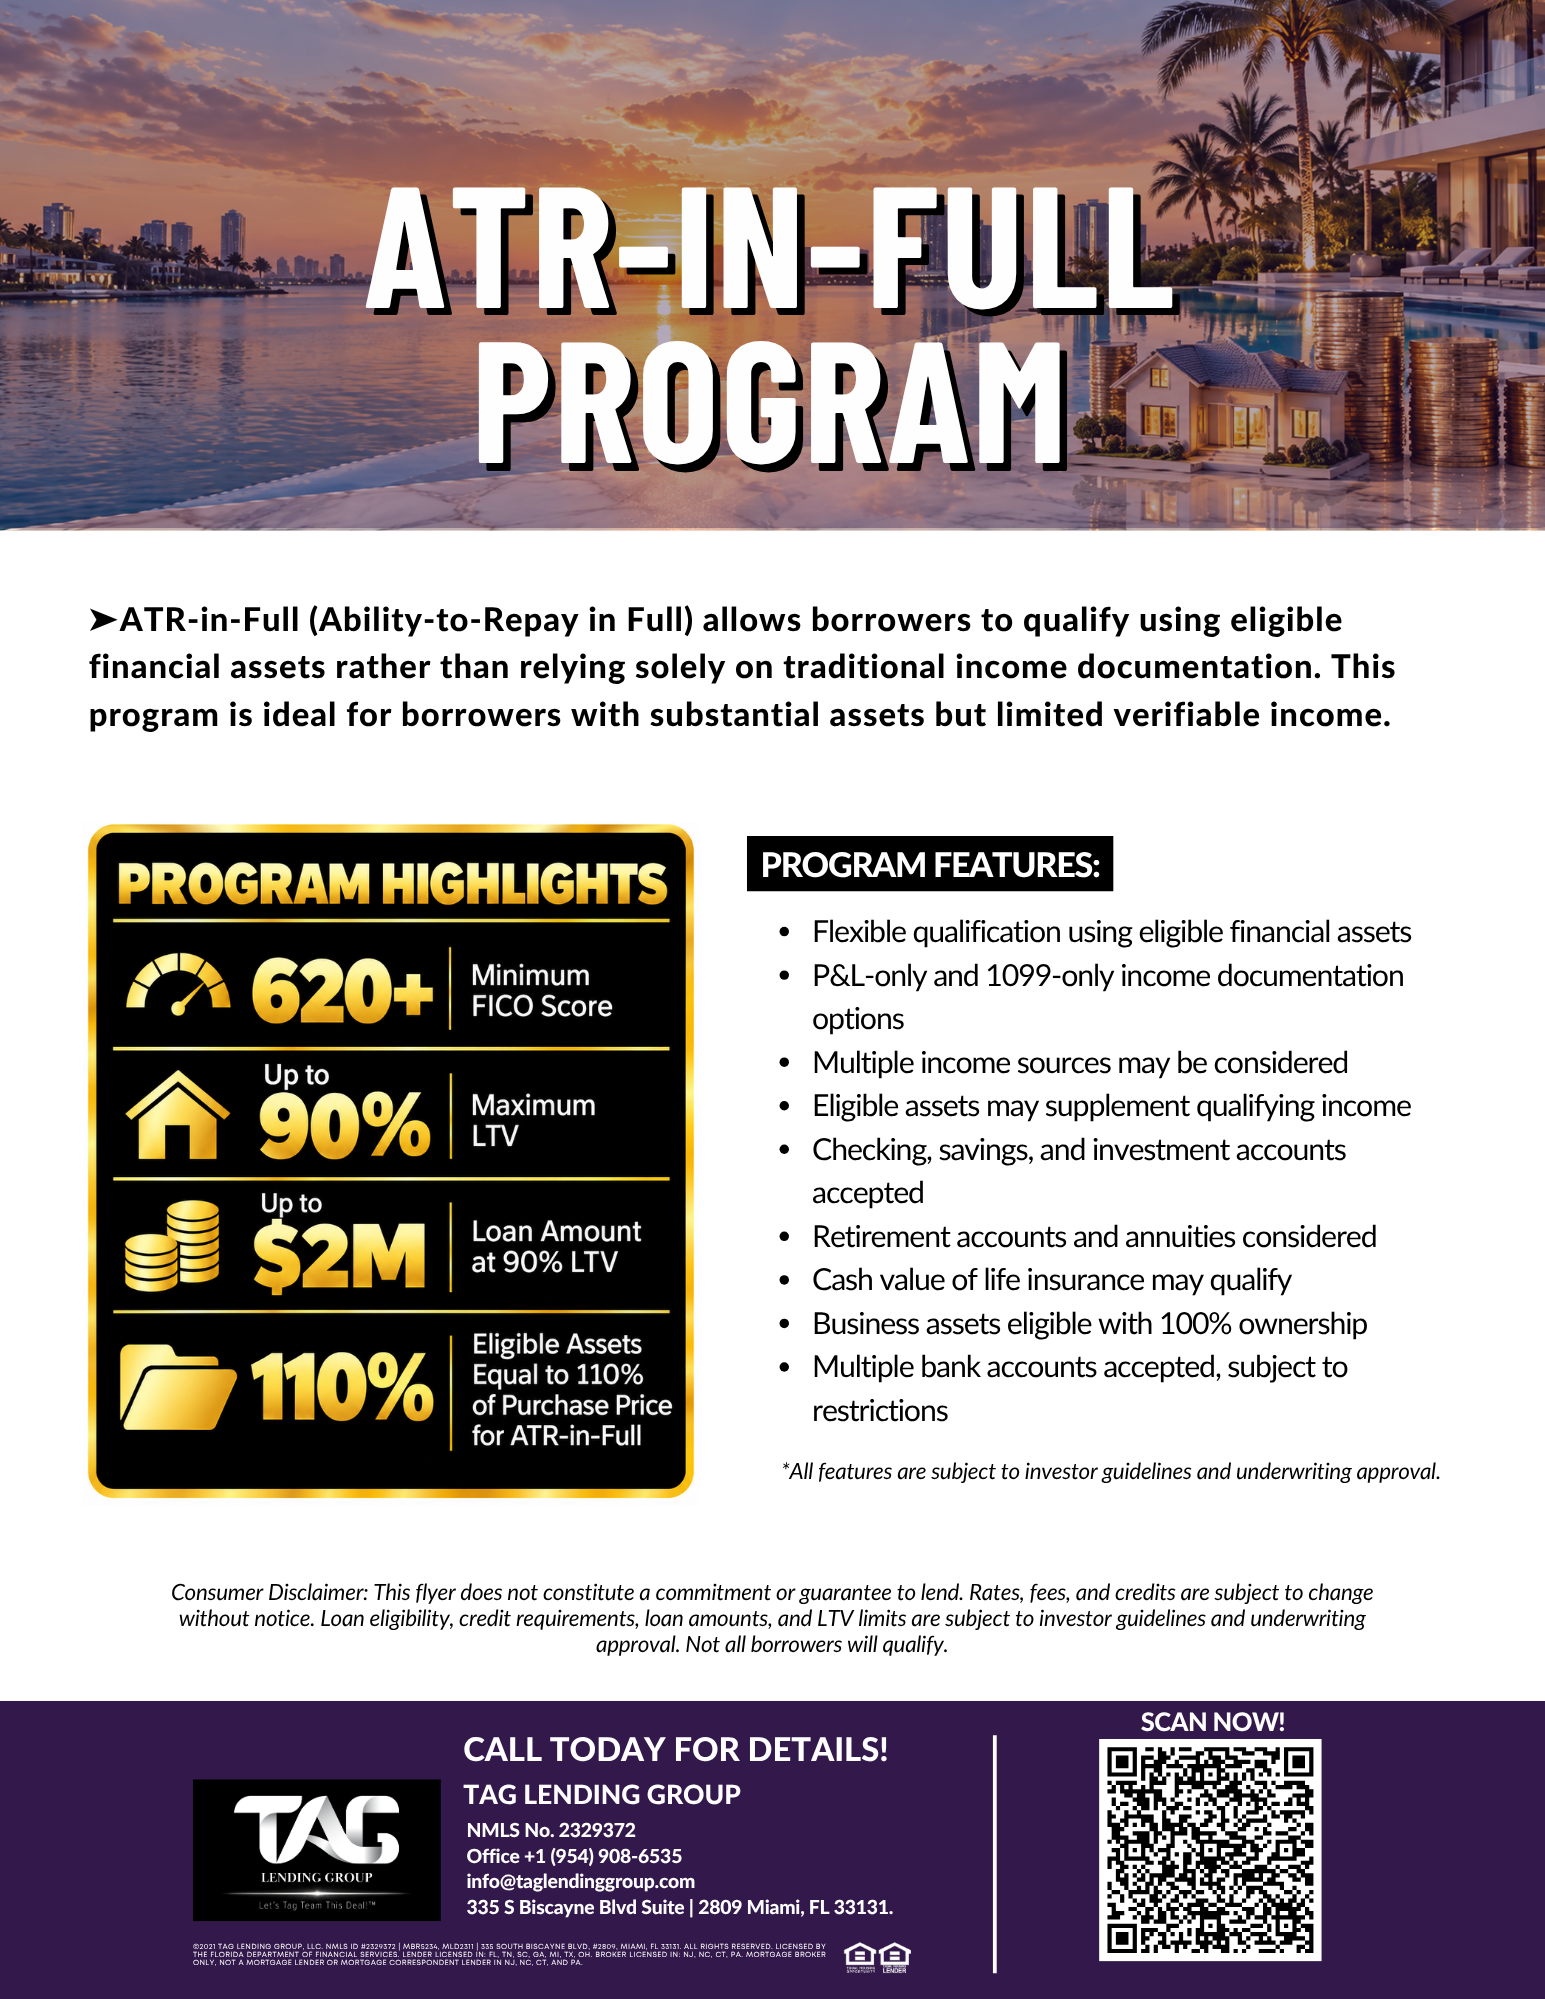
One option worth exploring is the ATR-in-Full Program, which considers eligible financial assets when evaluating mortgage qualification.
What Is the ATR-in-Full Program?
-
ATR-in-Full, or Ability-to-Repay in Full, is a mortgage financing option designed to consider qualifying financial assets as part of a borrower's ability to repay a loan.
-
Unlike traditional income-focused qualification methods, the program allows certain financial assets to play a role in determining mortgage eligibility.
-
This may benefit borrowers who have accumulated substantial wealth but whose documented income doesn't fully reflect their financial position.
What Types of Assets May Qualify?
Depending on investor guidelines, eligible assets may include:
Checking, Savings, and Money Market Accounts
-
Funds held in eligible deposit accounts may be considered when evaluating a borrower's financial resources.
Stocks, Bonds, and Mutual Funds
-
Eligible investment portfolios may also contribute toward mortgage qualification.
Retirement Accounts and Annuities
-
Certain retirement assets may qualify, with valuation percentages depending on the borrower's age.
Cash Value of Life Insurance
-
The eligible cash value of a life insurance policy may be considered as part of the borrower's financial assets.
Business Assets
-
Certain business assets may qualify when the borrower owns 100% of the business, subject to program requirements.
How Does Asset-Based Mortgage Qualification Work?
-
Instead of relying exclusively on traditional employment income, an asset-based qualification approach considers the value of eligible financial assets.
-
For example, a borrower may have significant savings and investment accounts but relatively limited income reflected on tax returns.
-
Under an eligible asset-based program, those financial resources may help demonstrate the borrower's ability to meet mortgage obligations.
-
Not every asset is counted at its full value. Applicable valuation percentages, ownership requirements, documentation standards, and other investor conditions determine how assets are evaluated.
Who Might Benefit From ATR-in-Full?
This financing option may be worth exploring for several types of borrowers:
Retirees
-
Individuals who have accumulated retirement savings and investment portfolios but no longer receive traditional employment income.
Self-Employed Borrowers
-
Business owners whose reported income may not fully reflect their accumulated financial resourcesS
Investment Portfolio Holders
-
Borrowers who hold substantial savings, stocks, bonds, or mutual funds.
Asset-Rich Borrowers With Limited Documented Income
-
Individuals with significant financial resources who may have difficulty qualifying through conventional income documentation alone.
Why Consider Alternative Mortgage Financing?
-
Every borrower has a different financial situation.
-
Traditional income documentation remains an important part of many mortgage programs, but it doesn't always capture the complete financial picture.
-
Alternative financing programs can provide additional ways to evaluate borrowers based on their unique circumstances.
-
For those with substantial eligible assets, ATR-in-Full may offer an opportunity to explore mortgage financing beyond conventional income qualification methods.
Explore Your Mortgage Options With Tag Lending Group
-
At Tag Lending Group, we understand that mortgage financing isn't one-size-fits-all.
-
Whether you're self-employed, retired, or managing a substantial investment portfolio, our team can help you explore financing options that align with your financial goals.
-
If traditional income documentation doesn't reflect your complete financial picture, the ATR-in-Full Program may be worth considering.
-
Ready to Explore Your Mortgage Options?
Schedule a Meeting With Anthony Angelillo
Let's TAG TEAM This Deal!
Disclaimer: All loans are subject to credit approval, underwriting requirements, asset verification, investor guidelines, and program availability. Not all borrowers will qualify. Tag Lending Group, LLC | NMLS #2329372.
Download Our Cheat Sheet!


Unlocking Real Estate Success:
Tag Lending Group's Client Funnel Retention Program
In this dynamic video, we break down the essential components of our intake form and showcase how it empowers you to understand your return on investment, lead sources, and client demographics. Discover how we harness this data to fine-tune your marketing strategy and drive impressive results.🏠🔑